
Plynk: Grow as an Investor
- Rating
- 4.1
- Downloads
- 500.00K
- Content Rating
- Everyone
Plynk: Grow as an Investor - Screenshots
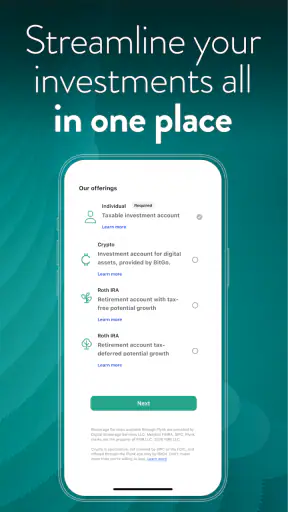
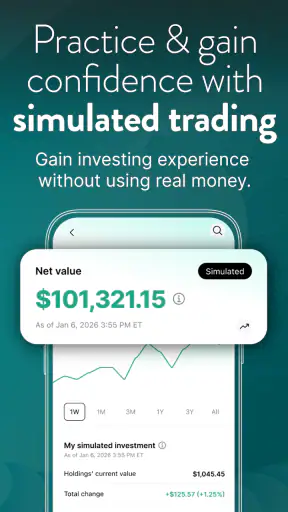
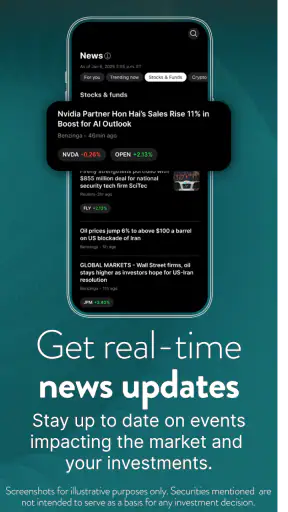
Pros
- Simple interface makes investing approachable for beginners.
- Offers fractional shares
- allowing investment with small amounts.
- Recurring investments can help users build consistent saving habits.
- Provides educational content to support learning about investing.
- Supports diversified portfolios across various assets and companies.
Cons
- Investment values can fall
- so returns are not guaranteed.
- Fees or spreads may reduce returns depending on the selected service.
- The app may offer fewer advanced tools for experienced investors.
- Identity checks can delay account setup and initial deposits.
- Availability and features may vary depending on your country.
Plynk: Grow as an Investor - Description
- App Name
- Plynk: Grow as an Investor
- Package Name
- com.dbs.plynk
- Developer
- Digital Brokerage Services LLC
- Category
- Finance
- Last Updated
- Apr 14, 2021
- Version
- 4.5.0
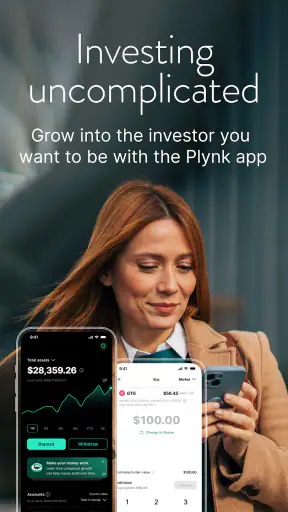
I approached Plynk: Grow as an Investor as a beginner-friendly finance app rather than as a replacement for a full trading workstation. That distinction matters. Its appeal is the attempt to make investing feel less intimidating, with a cleaner learning path and tools that are easier to approach than the dense screens found in many traditional brokerage apps. After spending time with it, I see the strongest value in helping a new investor move from “I should probably learn this” to a repeatable routine for researching and following investments.
The app is free, carries an Everyone age rating, and comes from Digital Brokerage Services LLC. It has built a sizable audience, with more than half a million installs and an average score of 4.1 from roughly four thousand ratings. Those figures suggest a product that is accessible enough for everyday users, although they should not be confused with proof that it suits every investing style. Plynk is most useful when you want clarity and education alongside investing tools, not when you need every advanced control available from a professional platform.
Starting with a simple investing routine
The best way to use Plynk is to begin with a narrow purpose. I would not open it expecting to understand every market concept in one sitting. Instead, I would choose one goal: learn how a particular investment works, build a small watchlist, or create a habit of reviewing a portfolio without reacting to every market movement. This approach keeps the app from becoming another source of financial noise.
A practical first session looks like this: explore the educational material, identify a few companies or funds that interest you, and write down why they caught your attention before making any decision. That small pause is useful because it separates curiosity from a plan. If the reason is simply that something appeared popular, I would keep researching rather than rushing ahead. If the reason is connected to a long-term objective or an area I understand, the next step becomes more deliberate.
What I like about this workflow is that it gives the app a job beyond placing transactions. Many finance apps push users quickly toward charts, price changes, and action buttons. Plynk’s emphasis on clarity and education makes it more comfortable for someone who still needs to translate basic investing language into plain English. I found that especially helpful when comparing an investment idea with my own risk tolerance instead of treating a rising price as an automatic recommendation.
I would also set a regular review time rather than checking constantly. A short weekly session is enough for many beginners: revisit the items being followed, read the relevant learning material, and note whether the original reason for watching them still makes sense. This habit is more valuable than repeatedly opening the app during a volatile day. It encourages a process that can survive market excitement.
Who gets the most from the basic experience
Plynk is a good match for someone opening a first investing account, someone who finds conventional brokerage interfaces overwhelming, or an existing investor who wants a less intimidating place to refresh the fundamentals. It can also suit a person who learns best by combining short explanations with a practical look at investments rather than reading a long textbook first.
It is less convincing for a frequent trader who depends on highly detailed analysis, rapid order management, or a deep collection of professional research tools. A simplified interface is an advantage until simplicity starts removing information you need. Experienced investors may still appreciate the approachable presentation, but they should compare it with their current broker before moving an established workflow.
One important expectation to set early is that education does not remove investment risk. The app can make concepts easier to understand, but it cannot turn uncertain assets into predictable ones. I would use its learning tools to improve my questions, not to outsource decisions. That mindset prevents the friendly design from becoming a reason to invest without doing enough personal research.
Settings and choices worth checking before building a habit
Although the main attraction is the straightforward experience, I would spend a few minutes reviewing the app’s available account and notification choices before using it regularly. The exact options visible to you can depend on your account and device, so I would not assume every setting is equally important. The general principle is simple: keep alerts useful enough to support your routine, but not so frequent that they encourage impulsive checking.
If notifications are enabled, I would decide which ones genuinely help me. An alert that reminds me to review something may be useful; a stream of short-term price movement notices may pull me toward decisions I never intended to make. For a beginner, controlling that noise is an investing skill in itself. The most polished interface cannot compensate for a habit built around reacting to every notification.
I would also check how the app presents educational content and whether I can return to topics that were unclear. A useful technique is to revisit a lesson immediately after looking at an investment related to that subject. For example, after reading about diversification, I would compare that idea with the holdings or companies I am considering. Learning becomes more memorable when I apply it to a real question instead of treating each explanation as a standalone definition.
Another worthwhile check is the information shown before confirming an action. I would slow down at that point and read the details rather than treating the final screen as a formality. This is where an approachable app should still be treated like a financial tool. Confirming what I am doing, why I am doing it, and whether it fits my plan is a better safeguard than relying on the app’s friendly presentation.
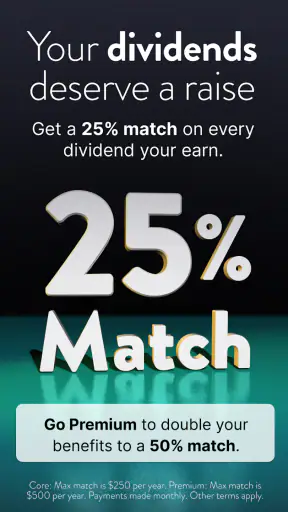
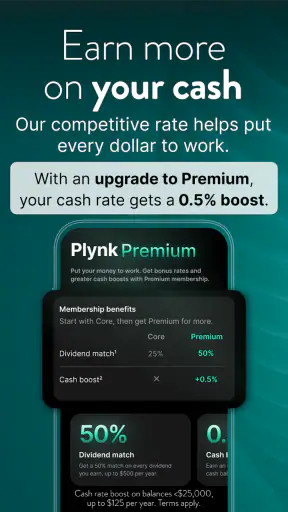
The app is free to download, but “free” should not be interpreted as “without financial consequences.” The important costs in investing come from the decisions and assets involved, not merely from installing the software. I would read the relevant account and transaction information presented inside the service and make sure I understand what applies to my situation before committing money.
A settings habit that improves decision quality
My preferred setup would be intentionally boring. I would keep only the information I need for a weekly review, organize my watchlist around actual goals, and avoid adding every interesting company I encounter. A smaller list creates a useful constraint: each item has to earn its place by giving me something worth researching.
I would also separate “learning” from “ready to act.” An investment can remain on a watchlist while I learn about it. That distinction is easy to lose in an app designed to make the next step accessible. Keeping a written note beside each idea—what I understand, what I still need to check, and what would change my mind—turns the app into part of a decision process rather than the decision process itself.
Faster patterns for repeat users
Once the initial setup is complete, the fastest users are not necessarily the ones who move through screens most quickly. They are the ones who repeat a clear sequence. I would use the same order every time: review the goal, check the relevant information, revisit the reason for the investment, and only then consider an action. Repetition reduces the temptation to improvise when the market is moving.
A useful pattern is to group research into themes instead of browsing randomly. If I am interested in a particular sector, I would first learn the basic terms, then compare a small number of ideas, and finally decide whether the sector belongs in my broader plan. This makes Plynk’s educational angle more practical because each lesson answers a question I have already encountered.
Another efficient habit is to use the app as a checkpoint after reading elsewhere. I might encounter an investing idea in a news article or conversation, but I would not treat that source as enough. I would bring the idea into Plynk, look at the available information and learning context, and ask whether I can explain the investment in my own words. If I cannot, I am still researching rather than making a confident decision.
This is also where the app can work well for a busy person. Imagine checking your finances on a Sunday evening after household planning. You could review a small watchlist, revisit one educational topic, and record whether your chosen investments still align with your goal. That routine takes less mental energy than trying to reconstruct your entire financial picture every time the market changes. The benefit is not speed alone; it is consistency.
I would avoid treating a watchlist as a collection of recommendations. A list is only a research queue. To make it useful, I would remove ideas that no longer fit my goals and keep a short note explaining why each remaining item is there. That creates an important friction point: before acting, I have to confront my original reasoning instead of following whatever looks most interesting today.
Where the friendly design helps—and where it can mislead
The approachable layout lowers the emotional barrier to learning. Someone who has avoided investing because brokerage apps look complicated may be more willing to explore concepts here. The educational framing can also help users recognize the difference between a company, a fund, a market movement, and a personal objective.
At the same time, a clean interface can make investing feel easier than it really is. Fewer visual distractions do not mean fewer financial questions. I would still consider time horizon, diversification, emergency savings, and the possibility of losing money. Plynk can organize the learning and investing experience, but it cannot decide how much risk belongs in a person’s life.
That trade-off is central to my view of the app. I prefer a clear interface when I am learning, but I would not choose it solely because it feels comfortable. Comfort is useful when it encourages careful research; it becomes a weakness when it encourages quick action without enough understanding.
Advanced limits and when another option is better
Plynk’s simplicity is not a universal advantage. Investors who need sophisticated charting, extensive order controls, specialized research, or a highly customizable professional workspace may outgrow it. In that situation, a full-service brokerage or a dedicated market-analysis platform could be a better fit. The right comparison is not which app looks nicer, but whether the available information and controls match the decisions you actually make.
I would also be cautious about using a beginner-oriented app as the only source for serious financial planning. Education inside the app can help with investing vocabulary and basic choices, but broader questions—such as tax planning, retirement strategy, debt priorities, or a household’s complete risk position—may require resources beyond an investing application. Plynk can be one part of that picture without being the whole picture.
Another limitation is psychological rather than technical. Because the app is designed to reduce friction, it may make it easy to move from interest to action. That is valuable for users who are stuck at the starting line, but it is a reason to create personal rules. I would decide in advance how long I want to research an unfamiliar investment, what information I need before acting, and when I will review the decision afterward.
The current version is 4.5.0 and requires at least iOS or Android version 12. That makes checking device compatibility part of the practical setup, particularly if you use an older phone or tablet. For supported devices, the app’s free entry point makes trying the workflow relatively easy. Still, I would evaluate it based on whether the experience remains useful after the first week of novelty has passed.
Privacy and account security deserve the same attention as the investing features. I would use a strong, unique password, protect the phone itself, and avoid signing in on devices I do not control. Those are basic precautions, but the fact that an app feels simple should never lower the standard for protecting a financial account.
Questions I would answer before choosing it
If you are wondering whether Plynk is suitable for a complete beginner, my answer is yes, provided you are willing to learn and accept that the app is not a shortcut to certainty. Its clearest strength is the bridge between educational material and an actual investing workflow. I would recommend starting with small, understandable goals rather than attempting to build a complicated portfolio immediately.
If you already invest elsewhere, I would ask whether you need a second platform for education and organization. Plynk may be worthwhile if your current broker feels crowded or difficult to learn. If your existing service already gives you the research depth and workflow you need, switching may add unnecessary complexity.
If you are mainly interested in frequent trading, I would probably look elsewhere first. The app’s clarity is more valuable for learning and repeatable investing habits than for a high-speed, detail-heavy strategy. A platform built around advanced analysis and execution may better match that use case.
If you are concerned about cost, the app itself is free, but that does not answer every question about the financial implications of using an investing service. I would inspect the account information and terms relevant to my circumstances before transferring money or making a transaction. Free access should be treated as an opportunity to evaluate the workflow, not as a guarantee that investing is costless.
Finally, if you are under the Everyone age guidance, I would still approach the service with adult-level care around financial decisions. An age rating describes accessibility, not suitability for every financial situation. The right time to invest depends on goals, knowledge, obligations, and risk—not simply on whether an app can be installed.
My verdict after building a repeatable workflow
The strongest reason to choose Plynk is that it turns investing education into something you can practice. I like it as a calm starting point for people who want to understand what they are doing, create a small research routine, and avoid the intimidating feel of a traditional brokerage screen. The combination of accessible tools and learning material gives beginners a sensible place to develop confidence without pretending that markets are simple.
My recommendation comes with boundaries. I would not use it as my only resource for complex financial planning, and I would not select it for advanced trading demands. I would also create my own pauses and review rules because an easy-to-use investing app can make action feel faster than judgment. Used thoughtfully, that friction can be managed through a consistent routine.
Digital Brokerage Services LLC has made a finance app that is easiest to appreciate when you use it deliberately: learn one concept, investigate a limited number of ideas, record your reasoning, and review decisions on a schedule. For a newcomer, that process is more valuable than a crowded collection of features. For an experienced investor, the question is whether the simplicity adds something missing from the current setup.
After weighing those trade-offs, I see Plynk as a strong learning-oriented companion and a reasonable first investing app, especially for someone who wants plain language and a manageable workflow. I would recommend giving it a trial on a compatible device, beginning with education rather than transactions, and judging it by whether it helps you make calmer, better-explained decisions. That is where this app is at its best.
FAQ
What is Plynk: Grow as an Investor?
Plynk: Grow as an Investor is an investing app designed to make the stock market easier to understand and access, particularly for people who are new to investing. It combines educational explanations with investment tools, allowing users to explore companies, learn basic concepts, and build a portfolio from a mobile device. The app is intended to simplify the process, but investing still involves risk and is not a guaranteed way to make money.
Can beginners use Plynk without previous investing experience?
Yes. Plynk is built with beginners in mind and presents investing topics in relatively simple language instead of assuming users already understand financial terminology. Its educational approach can help explain ideas such as stocks, funds, diversification, and market risk before users make decisions. However, the app should not replace independent research or professional financial advice, especially when investing larger amounts or choosing higher-risk assets.
What can I invest in through Plynk?
The investment choices available through Plynk may include individual stocks, exchange-traded funds, and other supported investment products, depending on the account type, location, and current platform offerings. Before downloading or depositing money, users should check the latest information in the official app listing and Plynk’s terms. Availability can change, and not every security or investment feature is necessarily accessible to every user.
Does Plynk charge fees for using the app or placing trades?
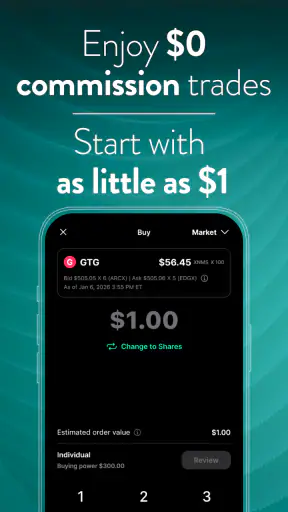
Plynk’s pricing can depend on the services you use, the type of account you open, and the rules in your region. Some basic features or trades may be offered without a visible commission, but other costs can still apply, including fund expenses, regulatory charges, currency conversion costs, or account-related fees. Always review the current fee schedule and transaction details inside the app before confirming an investment.
Is my money safe when I invest with Plynk?
Plynk may provide protections that apply to eligible customer accounts through its regulated financial partners, but these protections do not eliminate investment risk. The value of stocks and funds can fall, and market losses are generally not covered simply because an investment performed poorly. Users should verify which company regulates or holds their account, understand applicable investor-protection limits, and avoid investing money they may need immediately.


